Zetwerk Manufacturing Businesses Limited is going live for an IPO. It makes power transformers, solar torque tubes, laptops and motherboards for customers like Siemens Gamesa, NextPower and Acer India, and it runs 26 plants of its own in India, Spain, the USA and Germany
IPO Summary
| Zetwerk IPO Details | |
|---|---|
| IPO Date | 15th to 19th Oct, 2026 |
| Issue Type | Fresh Issue + OFS |
| Tentative Listing Date | 23rd Oct, 2026 |
| Price Band | ₹143 to ₹151 |
| Post Issue Mcap at ₹151 | ₹25,583 Cr |
| Total Issue Size | ₹5,012 Cr |
Introduction
A power transformer takes 36 to 42 months to buy in the USA and 30 to 36 months in India. That gap is the business. The manufacturing capacity is spread across many small, uncoordinated factories, which makes it slow to scale.
A manufacturing platform may try to fix this by pooling that capacity under one system. Such platforms are valued at ~₹12.57 lakh Cr in India in FY26, rising to ₹20 lakh Cr by FY31.
Meanwhile for the USA, it is just ~₹6.26 lakh Cr in FY26, but estimated to rise to a massive ~₹31 lakh Cr by FY31.
Zetwerk Manufacturing Businesses Limited is listing to serve that market. They’re going live in an IPO consisting of a Fresh Issue of ₹2,830 Cr and an Offer For Sale of ₹2,182 Cr, from 15th to 19th Oct, 2026.
Business Model
Zetwerk is a technology-led, asset-light, manufacturing platform.
- A company, say a solar developer or a laptop brand, sends Zetwerk a design for a part it needs, such as torque tubes, transformers or motherboards.
- Zetwerk’s software splits the order across many small factories, about 7 per order on average, and a few plants Zetwerk owns itself.
- It checks quality, ships the goods and handles the paperwork.
- The customer pays Zetwerk, and Zetwerk pays the factories. Zetwerk keeps the gap
The company calls the result a “universal factory”.
They draw on 6,979 third-party suppliers in 26 countries and on 26 plants that Zetwerk owns in India, Spain, the USA and Germany.
Since its start in 2017, it has delivered goods worth ₹74,374 Cr.
How an order moves:
- Order in: Customers range from start-ups to large firms. Key customers include Siemens Gamesa, NextPower, CG Power, NTPC Renewable Energy and Acer India.
- The Split: One order goes to several suppliers at once. The average order went to 7 suppliers in FY26. This shortens delivery time.
- Screening and Control: Zetwerk screens suppliers, inspects output, and handles logistics, customs and paperwork. Supplier orders are mostly fixed-price purchase orders with no price escalation, and suppliers face liquidated damages for late delivery.
Zetwerk books revenue when the product is made and delivered.
Zetwerk has (or, used to have), three segments:
- The Manufacturing Business earned 59% of revenue. This has three verticals: Energy Products, Precision Products, and Capital Goods. Energy Products are the biggest source of revenue from this.
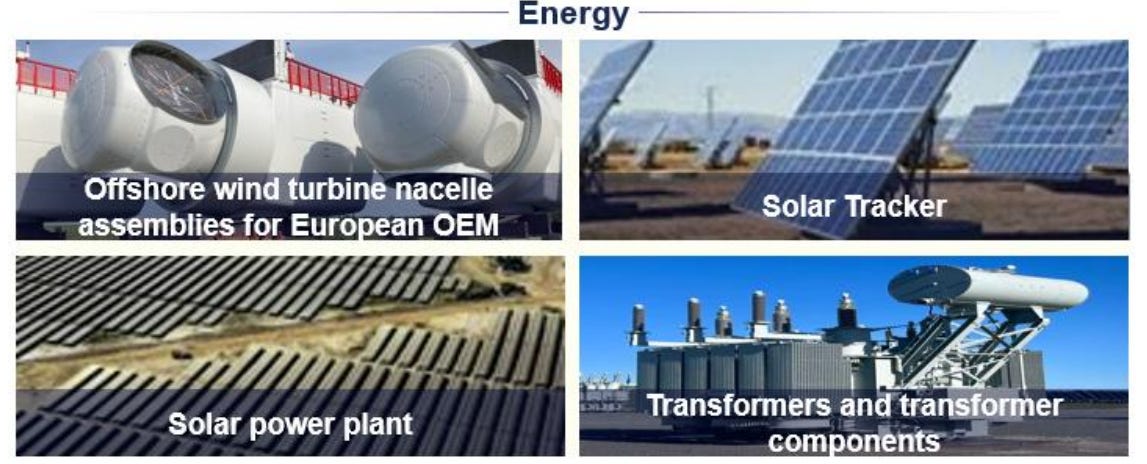
Source: RHP - The Ecosystem Business, branded Terra91, earned ~41% of revenue. This segment sells metals and petrochemicals such as aluminium, zinc, steel, copper and lead.
- A third segment (now closed): Zetwerk is discontinuing Civil Infrastructure Works, which built water pipelines and railway tracks.

Unit Economics

- Average order value rose from ₹4.59 Cr in FY24 to ₹9.17 Cr in FY26, almost doubling.
- Direct costs grew substantially in FY26. This includes freight, direct wages and subcontracting. Contribution Margin fell from 9.09% in FY25 to 8.17% in FY26.
- After other operating costs of ₹0.51 Cr per order, Adj. EBITDA per order was ₹0.24 Cr in FY26, though up from ₹0.04 Cr in FY24.
Operating Metrics
- New Orders/Revenue was 1.48x in FY24, and 1.64x in FY26, so Zetwerk has won more orders than it delivered in every year, which keeps the order book growing.

- Within the Manufacturing Business; Energy Products the top earner, but Capital Goods and Precision Products also make a good chunk of revenue.

- Manufacturing revenue grew from ₹6,082 Cr to ₹9,375 Cr (CAGR 24.2%) while Ecosystem stayed near ₹6,500 Cr (CAGR 2.0%

The Financial Stuff

- Revenue went up from ₹12,364 Cr in FY24 to ₹15,913 Cr in FY26, a CAGR of 13.4%.
- Exceptional Items and Finance Costs are the biggest costs. Zetwerk funds its large working capital with ~₹5,208 Cr of borrowings. The FY26 ₹836 Cr exceptional item is mainly a non-cash share-conversion charge.
- Loss from discontinued operations: FY26 loss includes a ₹453 Cr impairment on the civil infrastructure business being closed.
- Net loss: ₹918 Cr in FY24, ₹371 Cr in FY25 and ₹1,606 Cr in FY26, a CAGR of 32.3%.
Zetwerk’s Peers (FY26)

- Zetwerk is the only loss-maker. Its net loss is 10% of revenue and RoNW is negative 21%, while every peer earns a positive return.
- Dixon is the closest on margins. It earns only 3% PAT margin, yet its RoNW is 31% because it turns over capital very fast on thin margins.
- Suzlon Energy leads on every measure. Its FY26 profit includes a one-off deferred tax gain of ₹742 Cr.
Key Risks
- Piling Losses: Zetwerk lost ₹853 Cr, ₹215 Cr and ₹964 Cr from continuing operations in FY24, FY25 and FY26. The total net loss was ₹1,606 Cr in FY26 If these may continue if growth costs stay high.
- Discontinued Civil Infrastructure business: The business lost ₹642 Cr in FY26 and ₹669 Cr in Q1FY27. The sale value is expected to be below the net asset value, so more write-downs are possible.
- Rising Debt: The company will use ₹2,160 Cr of the ₹2,830 Cr Fresh Issue to repay debt. The rest goes to acquisitions that are not yet named and to general purposes.
- Thin margins: Adj. EBITDA margin was ~3% in FY26. The Ecosystem Business is 41% of revenue, at just a ~1% EBITDA Margin, so small shifts in price or cost can erase profit.
- Reliance on third-party suppliers: Products sourced from third parties were 80% of FY26 revenue. Purchase orders are short term with no fixed commitments, and suppliers can divert supply. Metals prices and exchange rates add to the risk.
- Plant and permit issues. The Greater Noida plant is suspended while it moves to Manesar, which the company expects to finish in FY27. Some approvals for other plants, including a fire clearance for a Kryfs Power unit, are still pending.
Conclusion
Zetwerk pools factories into one network and has grown revenue 13% a year over two years, with its order book at ₹13,062 Cr. Profit has not followed: Adj. EBITDA margin is low, and the net loss was ₹1,606 Cr. Part of the proceeds will be used to cut debt.