The following article is for educational purposes ONLY. Each and every piece of information used henceforth in this article was sourced from the DRHP and/or RHP.
IPO Summary

Introduction
The National Stock Exchange (NSE) needs no introduction. It is the exchange where almost every Indian investor trades and is India’s largest stock exchange by far.
NSE handles 92.99% of cash market turnover, nearly 100% of equity futures turnover, all exchange traded currency options activity, and more than half of all equity derivative contracts traded globally.
Despite its dominant position, NSE has never been a publicly listed company. That is set to change now that it’s going live in an IPO, consisting entirely of an Offer for Sale (OFS) worth ~₹22,562 Cr by existing shareholders, giving investors an opportunity to invest in India’s largest stock exchange.
The NSE Timeline

Business Model
NSE operates the exchange that hundreds of millions call their trading home. They are involved in clearing trades, providing market data and connectivity, licensing its indices, and lists companies for IPOs; all in addition to facilitating the largest amount of transactions in India on a daily basis.
The Revenue Model
NSE’s Revenue from Operations declined slightly in FY26, driven mainly by smaller transaction charge revenue. But where does this revenue come from?

Transaction Charges
Transaction charges are NSE’s single largest revenue line by a wide margin, accounting for ~79% of Revenue from Operations in FY26.
And out of these charges, the largest piece of the pie, by far, is from Options.

Landscape
India’s Growth & Scope
NSE’s growth story is, in large part, also India’s retail-investing story.
As financial markets become increasingly accessible to the retail investor and also as financial literacy continues to rise, investing in financial assets is seen as a better deal by a lot of Indians today as opposed to the past.

In fact, the number of unique investors on NSE has more than tripled in five years.

Global Scale: Goliath in Volume, David in Income
NSE just doesn’t charge as much of a fee per trade as other exchanges. Indian exchange fees per trade/contract are calibrated for high-volume, price-sensitive retail flow. This creates a unique dichotomy.
By number of trades in cash equities, NSE is the single busiest exchange globally ahead of giants like Nasdaq, ICE (NYSE), and Cboe.
NSE also ranked first globally in contracts traded in equity derivatives every year from FY2020 to FY2026, and held a global market share of ~51% of equity derivative contracts in FY26, which speaks to the Options hype in India.

On total income, NSE still ranks well behind the world’s large exchanges.

NSE’s global positioning is a dilemma. It’s the busiest exchange in the world by trade count, but one of the smallest by revenue.
Operating Metrics
Colocation
Colocation means letting some trading members (typically institutional clients) who want to host their servers physically inside or near NSE’s data centre to minimise latency.
Colocation was at the centre of a now settled SEBI investigation on NSE, alleging preferential data feed access for select HFT players. Regardless, NSE nearly doubled their capacity from 934 racks in FY24 to 1,680 racks in FY26.

Average Daily Trading Volume (ADTV)
ADTV tells the rupee amount that gets traded each day for each asset class. Futures & Options (F&O) dominates in this segment, mostly due to the huge trading.

IPO Listings
In FY26, Mainboard IPOs caught up to SME IPOs. Mainboard IPO activity was on the rise because SEBI implemented strict new rules causing the SME segment to cool down.

The overall growth in total listings is indicative of India’s appeal as a rising capital market, and in fact, the total money raised via IPOs through FY24 and FY26 increased by a CAGR of ~41%.

Future Growth Levers
1. Strengthening the core franchise
- Continuing to lead in cash equities and equity derivatives and focusing on growing new segments like Electronic Gold Receipt (EGR) framework, electricity futures, etc.
2. Diversifying beyond transaction fees
Since ~79% of revenue is still transaction-linked, other routes are sought by NSE, like:
- Data & analytics: Data feed terminals, connectivity services to trading members, brokers, and fintechs.
- Indices & licensing: Scaling Nifty-linked licensing revenue helps boost passive income. The AUM of passive funds linked to Nifty indices has already grown from ₹6.30 trillion in FY24 to ₹8.14 trillion in FY26.
- Colocation & technology infrastructure: Continuing to expand colocation capacity as more members seek low-latency access.
3. Technology and resilience investments
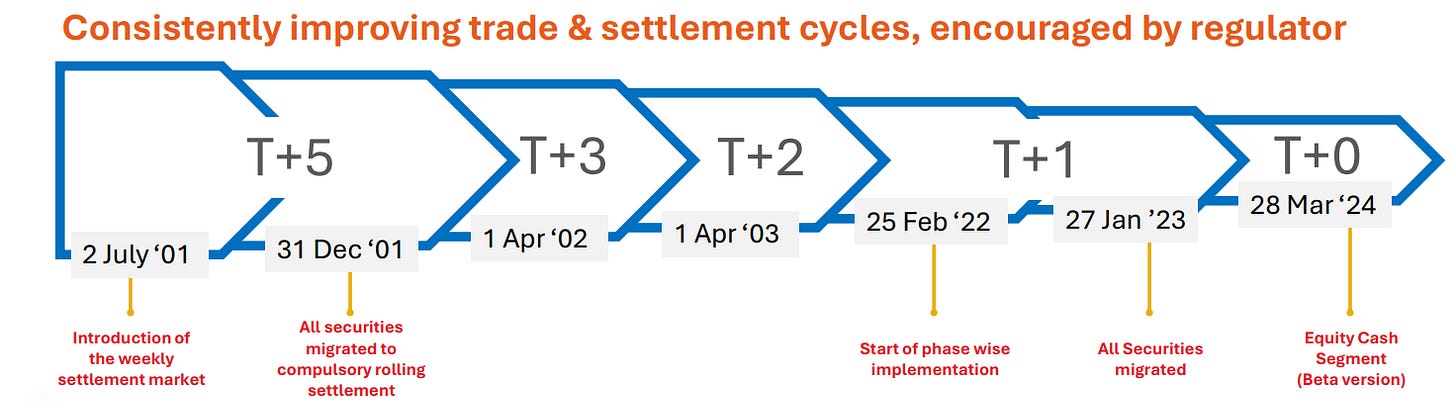
- Continued investment in trading, clearing, and surveillance technology, including participation in industry pilots for T+0 settlement and AI-based market surveillance.
Source: NSE Investor Presentation, May 2026 - Strengthening cybersecurity and business continuity infrastructure, given the systemic importance of NSE’s trading and clearing systems to the Indian financial system.

4. Forging global partnerships
- Building out NSE IFSC (GIFT City) as a gateway for global investors to access India-linked products.
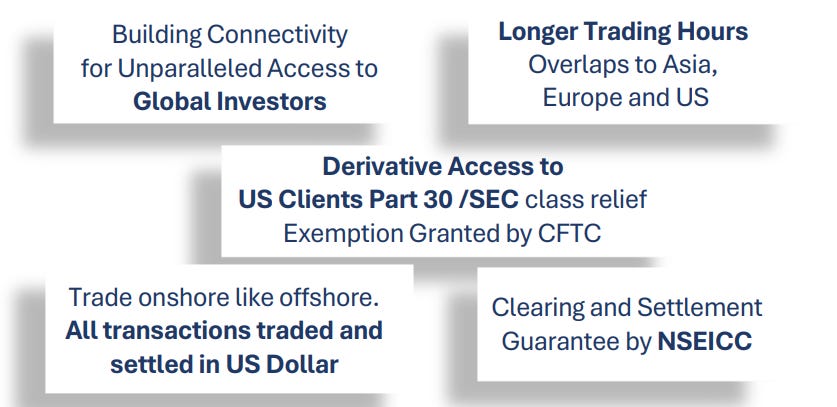
Benefits of NSE IFSC in GIFT City. Source: NSE Investor Presentation, May 2026

The Financial Stuff

- Revenue from Operations was ₹16,601 Cr in FY26, down 3.2% from FY25. This is mostly because SEBI’s October 2024 changes led to lower F&O trading volumes. Compared to FY24, it’s still on the rise
- On a similar trend, EBITDA are ₹11,098 Cr in FY26, which is a hike from FY24, but below the ₹12,647 level in FY25.
- And lastly, Profit After Tax was ₹10,302 Cr in FY26, up from ₹8,306 Cr in FY24, driven by revenue growth across transaction charges, listings, and data services.
Investors & Shareholding Pattern
NSE has no single identifiable promoter and was originally set up by a consortium of banks and financial institutions rather than a single promoter group.
The IPO itself is a pure Offer for Sale (OFS) of up to ~12.64 Cr equity shares by existing shareholders.
This actually marks a ~15% reduction from the originally proposed 14.89 Cr shares, as eight major investors, including SBI, MS Strategic, and Bank of Baroda, decided to significantly trim their planned stake sales.
Trading members and their associates, i.e., the brokers who use NSE’s platform daily, together still hold over a third of the exchange.
Top 10 Shareholders

Key Risks
1. Regulatory Concentration Risk
SEBI alone controls NSE’s fee structures, expiry days, lot sizes, and margin rules. The October 2024 derivatives rule changes cut F&O volumes. To a degree, earnings are exposed to decisions outside NSE’s control.
2. Enforcement Actions: Also adding to the above point, under SEBI’s scrutiny, NSE has faced and may face in the future show-cause notices, monetary penalties, and historical settlement proceedings (e.g., the now famous Colocation case) that threaten the exchange’s reputation.
Conclusion
Since exchanges can’t list themselves, NSE is going to be listed on the BSE. NSE may be the franchise doing big business, but FY26 results have already shown what regulatory tightening can do.
For a market that has spent three decades building the infrastructure for everyone else to invest, NSE’s own listing is, in some sense, the final box left to tick.