Glass Wall Systems (India) Limited is launching an IPO. The company runs a façade and fenestration business, designing, fabricating and installing glass and aluminium building envelopes. It supplies developers, contractors and corporates across India, the United States and Australia.
IPO Summary

Introduction
India is putting up office towers, airports, hospitals and luxury homes faster than it can find people to wrap them in glass and metal. Someone has to design, cut, fit and hang that outer skin, called a façade, on every one of those buildings.
Glass Wall Systems (India) Limited does that work. It calls itself the second-largest façade solutions provider in India by revenue and the country’s one of the largest façade exporters to the United States and Australia, and a newer bet on luxury windows and doors through an acquired subsidiary.
They’re now raising money through an IPO consisting of a Fresh Issue of ₹60 Cr and an Offer for Sale of ~₹368 Cr, from 8th to 10th Sep, 2026.
The Business Model
Glass Wall Systems runs three lines of business, all built around façades and fenestration, the industry term for windows, doors and other openings in a building’s outer wall.
- Domestic Façade Solutions: This includes curtain walls, cladding, skylights, canopies and aluminium doors and windows, with projects like Lodha World One, Kohinoor Square, The Capital and Bagmane Rio.
- International Façade Products Supply: For mostly the United States, the company manufactures façade panels in India and ships them to contractors abroad, with projects like Jackson Avenue and Harper Court.
- Fenestration Solutions: Through its subsidiary Yes Systems Private Limited, the company sells premium windows, doors, skylights and partitions under the ORIA brand for high-end Indian homes.

Revenue is mostly project-based, not repeat retail sales.
Manufacturing runs out of a single facility at Vile Bhagad in Maharashtra.
Most of the fresh issue proceeds from the IPO will fund a new in-house glass processing unit at that facility, a backward integration meant to cut reliance on outside glass suppliers.
Looking at the economics of its order book, the mix has shifted hard toward exports, i.e. international operations supplied ~22% of the order book.

Operating Metrics
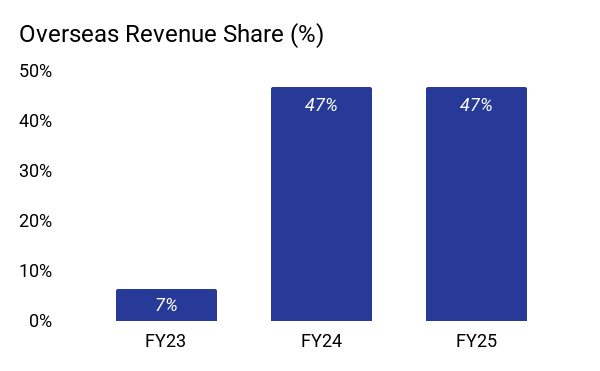
- Overseas revenue jumped from 7% of the total in FY23 to nearly 47% in FY24 and stayed stable in FY25, driven by the international façade supply business to the United States. This is the single biggest change in the company’s revenue mix over the period.
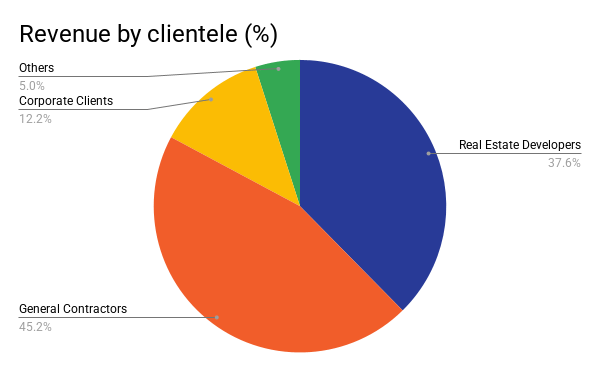
- General Contractors and Real Estate Developers dominate the revenue stream, collectively driving nearly 83% of total operations.
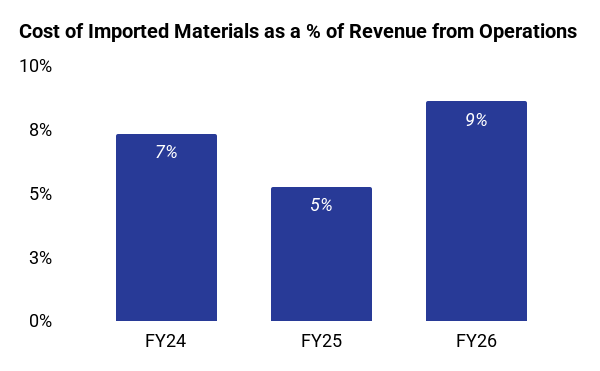
- Imports of raw materials grew to a three-year high of 9% of revenue in FY26, up from 5% in FY25, increasing the company’s vulnerability to currency fluctuations and global trade disruptions.


The Financial Stuff

- Revenue from Operations saw a slight contraction from ₹304 Cr in FY24 down to ₹278 Cr in FY25, before surging by roughly 64% to hit ₹457 Cr in FY26.
- Despite the revenue drop in FY25, EBITDA Margin actually went up that year, to 26% from 18% in FY24, and is at 23% in FY26 as well.
- Profit After Tax also quadrupled over the same period, from ₹20 Cr in FY24 to ₹84 Cr in FY26. Consequently, the PAT Margin also expanded from 7% to 18%.
Key Risks
- The offer is mostly an exit for existing shareholders: Of the ₹428 Cr offer, 86% is OFS, and ~₹60 Cr in fresh capital will reach the company, so most of the money raised does not actually fund growth.
- Revenue depends on a few large, project-based contracts and a small supplier base. Overseas revenue, worth close to 47% of the total in fiscal 2025, runs substantially through one collaboration partner in the United States, and domestic revenue depends on the timely award and execution of large projects. The company also has no long-term agreements with its raw material suppliers, leaving it exposed to price swings and supply disruption in glass and aluminium, both disclosed as risk factors in its own offer document.
Conclusion
Glass Wall Systems is a niche, high-margin façade and fenestration specialist that has used two decades of project experience to build a lead in Indian façade exports and a fresh foothold in luxury fenestration. Whether its order book can convert into projects without further margin slippage, and whether export concentration in the US stays stable will be important elements to look out for.